Q3 kicked off with a significant upward spike in rate and capacity volatility, hitting levels not seen since peak COVID-era shipping.
Though volatility slightly moderated throughout the quarter, the truckload market remained firmly in inflationary territory (significantly higher than last year).
In Q4, the overall demand picture remains muted against an uncertain economic backdrop, but sustained pressure on the supply side of the market (carriers) has created a tight environment for shippers — and peak season is fast approaching.
As we get into a new year, will we continue to see an even higher shift upwards in truckload market rates?
Has this truckload market cycle already peaked?
Should companies be dusting off their “Shipper of Choice” playbooks for 2027?
Q4 Truckload Market:
The Complete Guide for Logistics Pros
What you’ll learn in this comprehensive update:
- Q3 2026 truckload market recap
- Macroeconomic outlook
- 6 trucking trends to watch right now
- Q4 2026 truckload market forecast
- Curve infographic
New to the Curve?
These essential truckload market resources will give you foundational industry knowledge and teach you how how we build our proprietary spot rate index.
Want slides for your next presentation?
Download all the Curve charts and graphs, formatted for slides.
Spot & Contract Trucking Rate Recap: Q3 2026
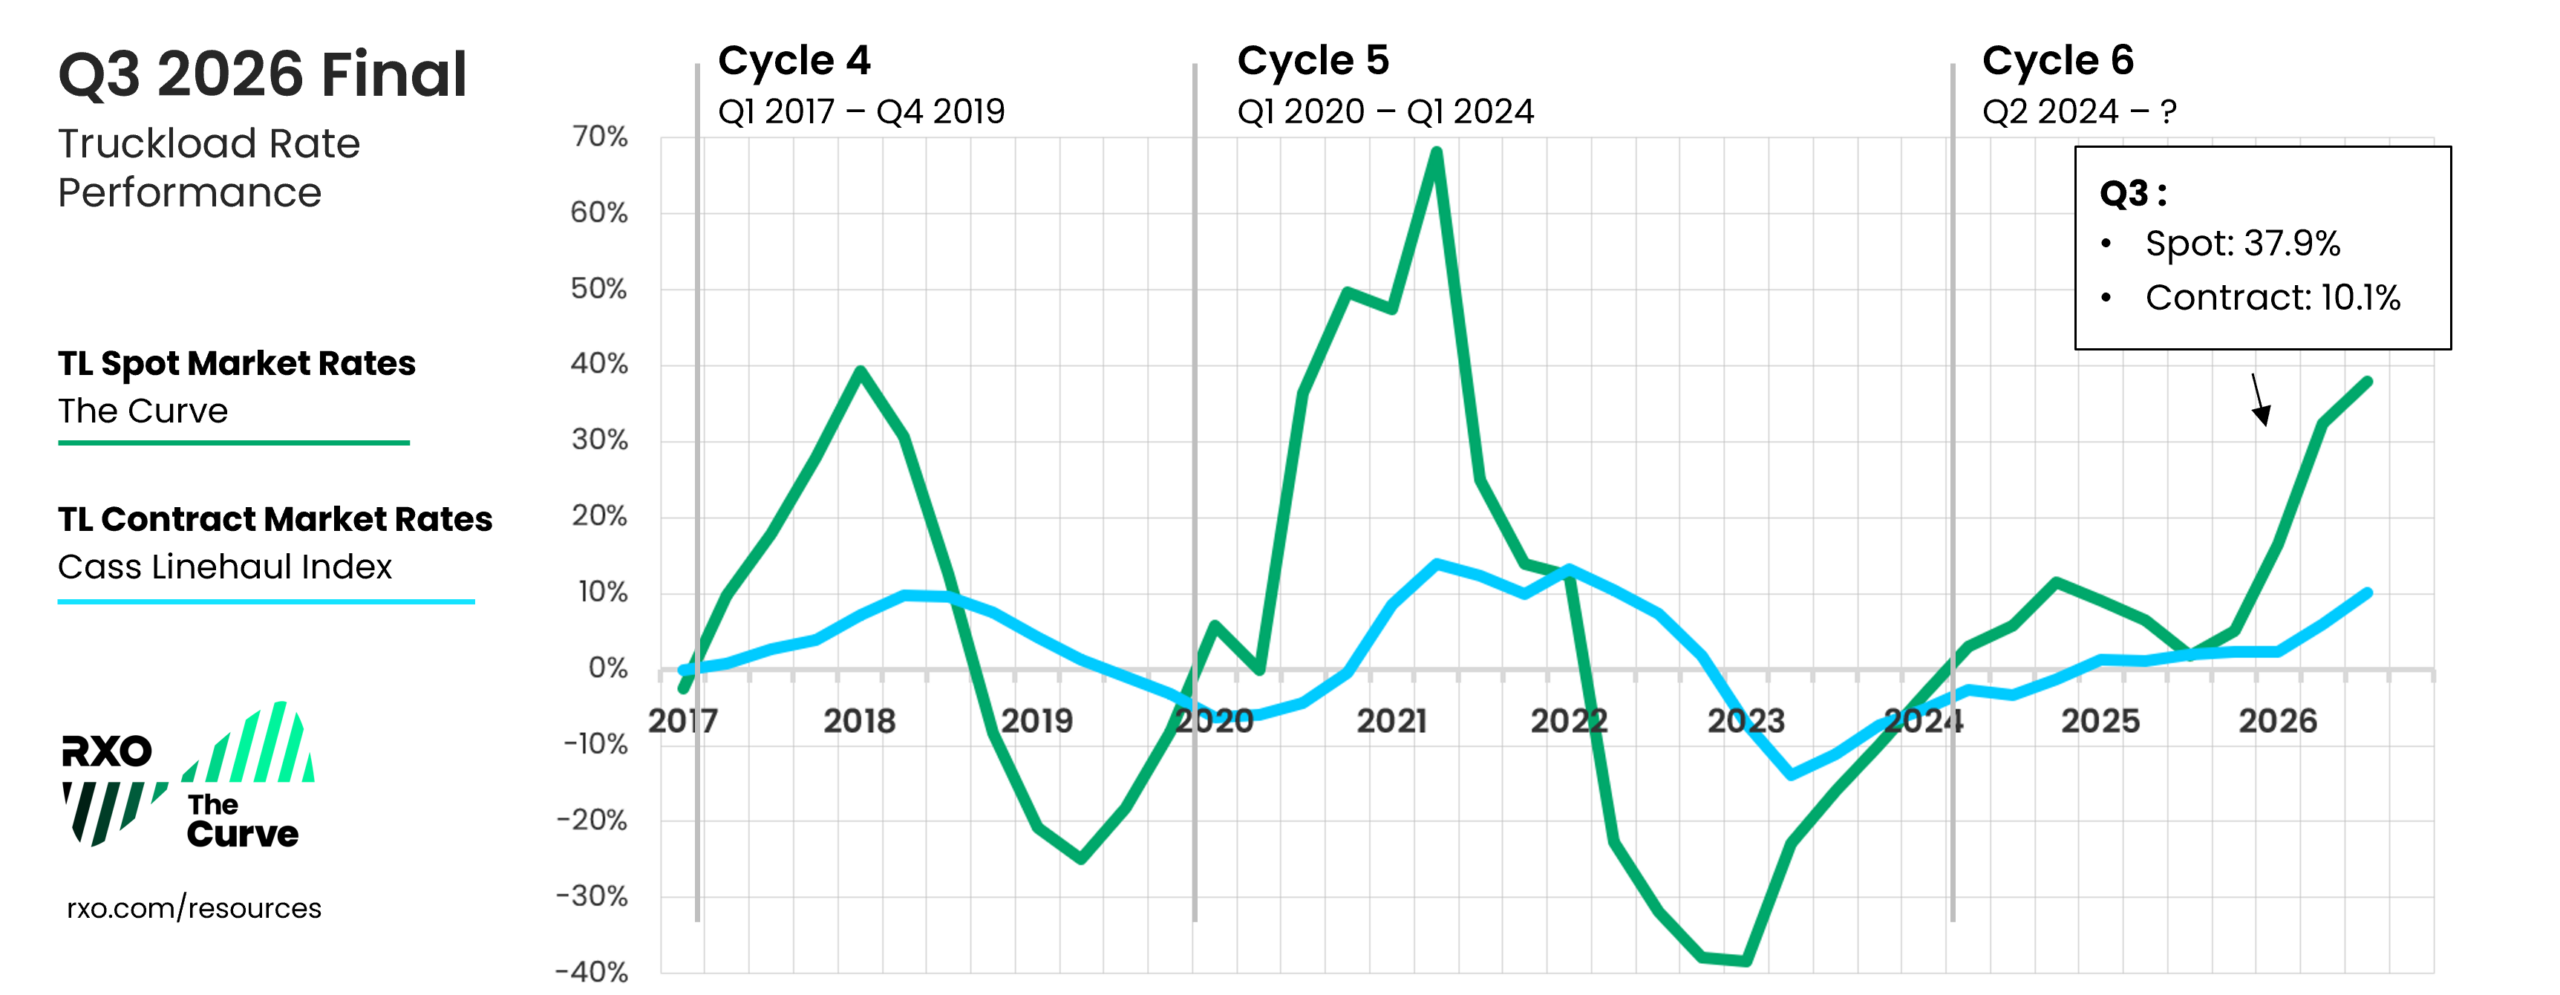
The RXO Curve index continued to move higher into year-over-year inflationary territory, notching its tenth consecutive inflationary reading and the highest reading since Q2 2021.
After a very volatile start to the quarter, conditions stabilized somewhat; however, the industry still experienced tight market conditions throughout, driving spot rate increases.
- Q3 truckload spot rates remained inflationary, up from Q2
Truckload spot rates, (linehaul only, excluding fuel), increased 37.9% year-over-year in Q3, up from 32.4% in Q2. - Q3 truckload contract rates remained inflationary, up from Q2
Truckload contract rates increased to 10.1% year-over-year, up from 6.0% in Q2. Continued spot rate inflation pulled contract along for the ride, as is typical for this stage of the truckload market cycle.
Download all the Curve charts for your next presentation.
Actual Spot Truckload Rates vs. Year-Over-Year
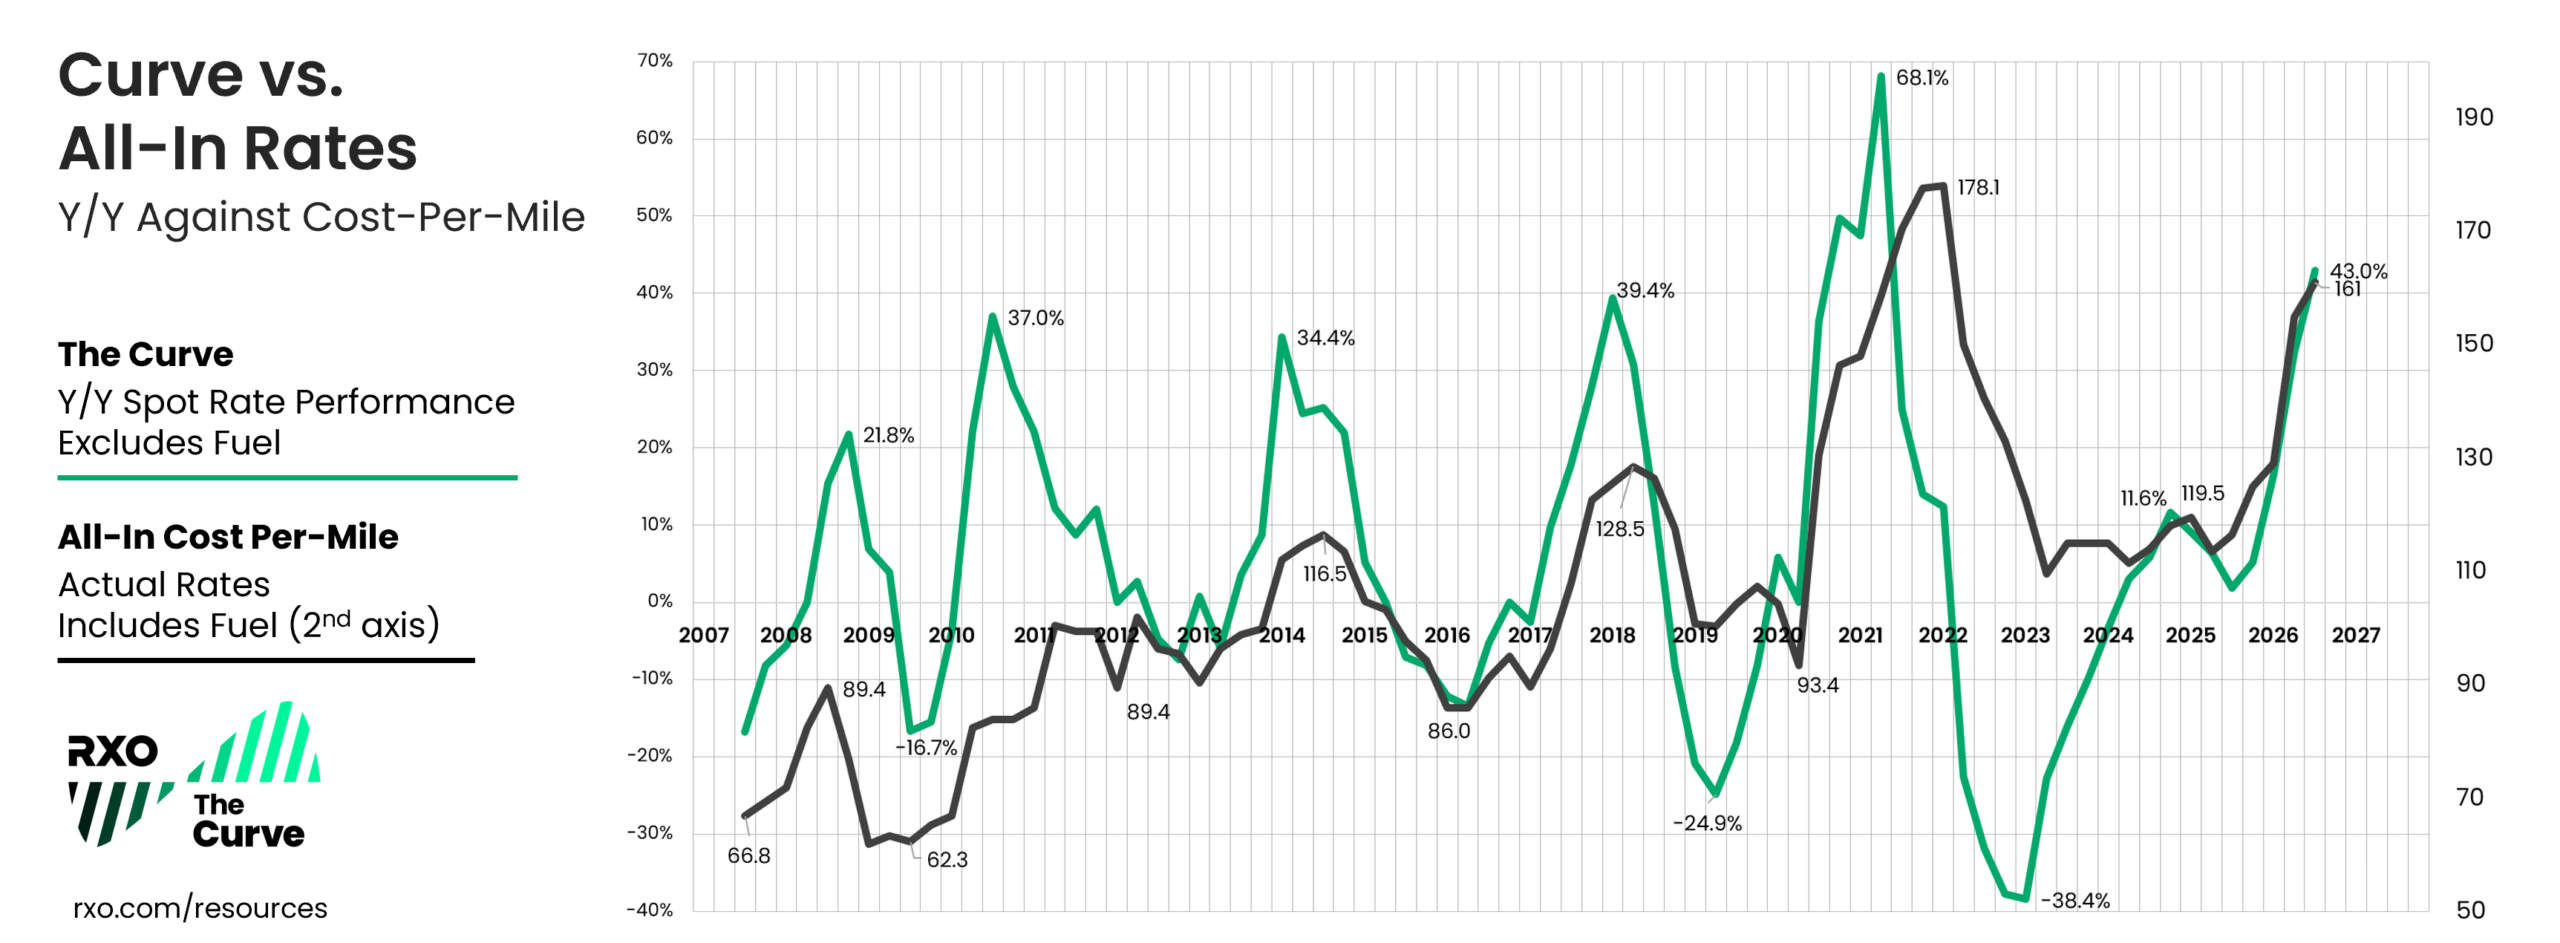
To build further confidence in the Curve (a year-over-year spot rate index), let’s see it up against our proprietary all-in cost-per-mile index — this is comparing annual change (without fuel) versus the actual rate (all-in cost, with fuel included).
The base value for the index is the 2015 annual average all-in cost per mile, and each quarter measures the percent change against that baseline over time.
As a reminder, these numbers are informed by real transactional data from thousands of daily shipments over the last 18 years.
During most of 2023, 2024 and 2025, this index was essentially flat, hovering around 115. For comparison, during COVID-era shipping in the early parts of the previous truckload market cycle, the index rose to a peak of 178.1.
At the end of 2025, the all-in index finally gained some momentum, and by Q2 2026, shot up to 154.9 — the highest reading since Q1 2022.
In Q3, the index ticked up even higher to 160.1.
While dramatically increasing fuel costs drove some of the increases over the past two quarters, diesel doesn’t account for all of the surge. A substantially higher cost structure has moved the baseline up for carriers, regardless of fuel costs.
Download all the Curve charts for your next presentation.
Q3 2026 Truckload Market: Key Takeaways
- The Curve (measuring year-over-year change in linehaul spot rates, excluding fuel) remained in inflationary territory and increased sequentially in Q3.
- All-in rates (actual amount paid to carriers) increased again, staying at their highest level in four years.
- Despite improving spot rates, carriers remained under significant cost pressure, exacerbated by higher fuel prices.
State of the Industry: Macroeconomic Overview
Overall, the U.S. macroeconomic environment remains in a similar spot as the last several quarters.
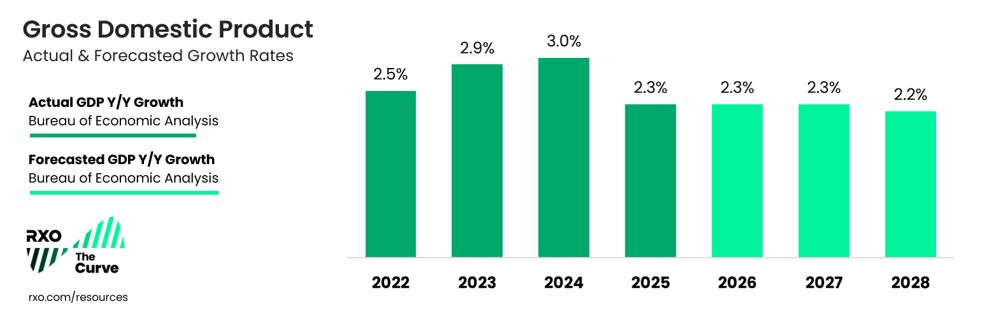
Through Q3, U.S. real gross domestic product (GDP) has remained stable, forecasted to finish the year at 2.3% growth year-over-year (though it has dipped from 2.6% in Q1 to 2.2% in Q2, and 2.1% in Q3).
However, stubborn inflation (exacerbated by fuel prices), elevated interest rates and ongoing geopolitical tension are producing a looming overhang of uncertainty and consumer anxiety.
Inflation & Interest Rates
Overall inflation across the U.S. economy remains persistently higher than the Federal Reserve’s target rate of 2%.
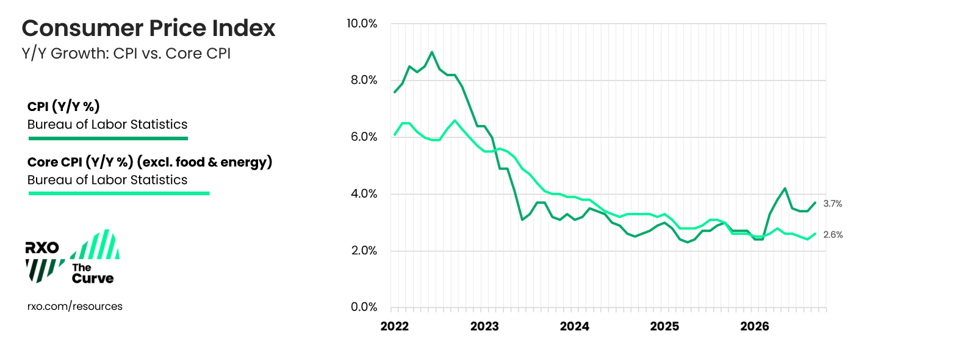
After rising to 3.0% year-over-year in September 2025, the Consumer Price Index (CPI) eased downwards for several months, getting as low as 2.4% in February this year.
However, inflation reversed course with the start of hostilities between the U.S. and Iran and the subsequent disruption of the global oil trade.
To put this in perspective, CPI inflation hit 4.2% year-over-year in May (a three-year high) driven largely by a sharp spike in fuel prices.
CPI inflation eased over the summer but then climbed back to 3.7% in September, and it remains elevated as higher energy costs have worked their way into transportation and travel prices. October offered little relief, as prices were up another 0.4% month-over-month.
While core inflation (which excludes volatile food and energy prices) has been more subdued relative to the headline number, it’s still above the Fed’s 2% target. In October, core inflation was up another 0.3% month-over-month and is running at an annualized rate of 3.7% over the last 3 months.
The Federal Reserve and Rate Cuts
After cutting rates by 25 basis points in December 2025 (bringing rates to their lowest level since 2022), the Fed kept rates steady for five consecutive meetings, including the first two under the new Chair of the Federal Reserve, Kevin Warsh, who began his term in May.
However, with inflation running persistently above target, the Fed raised rates 25 basis points at its September meeting.
Though it held rates steady at its most recent meeting on October 28th, financial markets are pricing in another rate hike of at least 25 basis points when the Fed holds its final meeting of the year (scheduled for December 8-9).
Consumer Confidence
Though overall consumer spending has been largely resilient, the compounding impacts of continued inflation, trade volatility from ongoing tariff implementation, and the war with Iran are taking their toll on the U.S. consumer’s outlook.
Consumer sentiment, as measured by the University of Michigan Consumer Sentiment Index, has been hovering around its lowest-ever readings for most of 2026.
For some context, the index dropped below 50 for the first time in its 74-year publication history in April, hit an all-time low of 44.8 in May, and has been in the 40s in five of the last eight months.
While the preliminary November reading ticked up to 51, a three-month high, it remains near the bottom of its historical range.
Ultimately, inflation and the trajectory of interest rates are inextricably linked to changes in both trade policy and geopolitical conflicts, both of which have been highly fluid. Until inflation eases, consumer sentiment is not likely to improve.
Industrial Demand
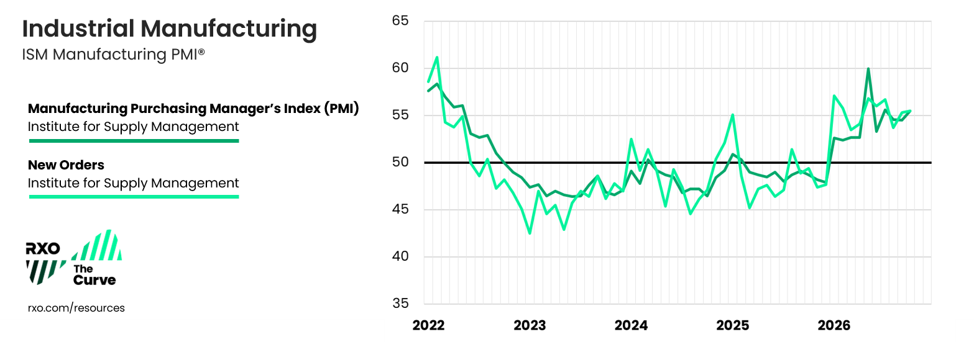
In January 2026, the Manufacturing Purchasing Manager’s Index (PMI) got off to a strong start, breaking a long period of contraction and jumping into expansionary territory (above 50).
This trend has persisted, with the index staying in expansionary territory every month this year. In October, the index hit 55.5, a full point increase from September (54.5).
Furthermore, the New Orders component of the Index, a leading indicator, has also been in expansionary territory all year, including a 55.5 reading in October (up slightly from 55.3 in September).
Overall, the continued relative strength in the industrial sector can be partially attributed to rapidly increasing demand for data center buildouts, along with semiconductors and defense.
This has been a bright spot for the overall freight economy and has helped offset weakness in other sectors (notably housing).
Key Economic Demand Indicators Driving the Truckload Market
Now that we’ve covered the broader economy, let’s look at some indicators that are most closely linked to truckload market activity.
Overall, we’ve seen modest, uneven growth in these indicators (with the exception of imports, which have been strong; more on that below). This has kept truckload volumes muted, and the freight market recovery to date has been driven primarily by tighter capacity rather than demand.
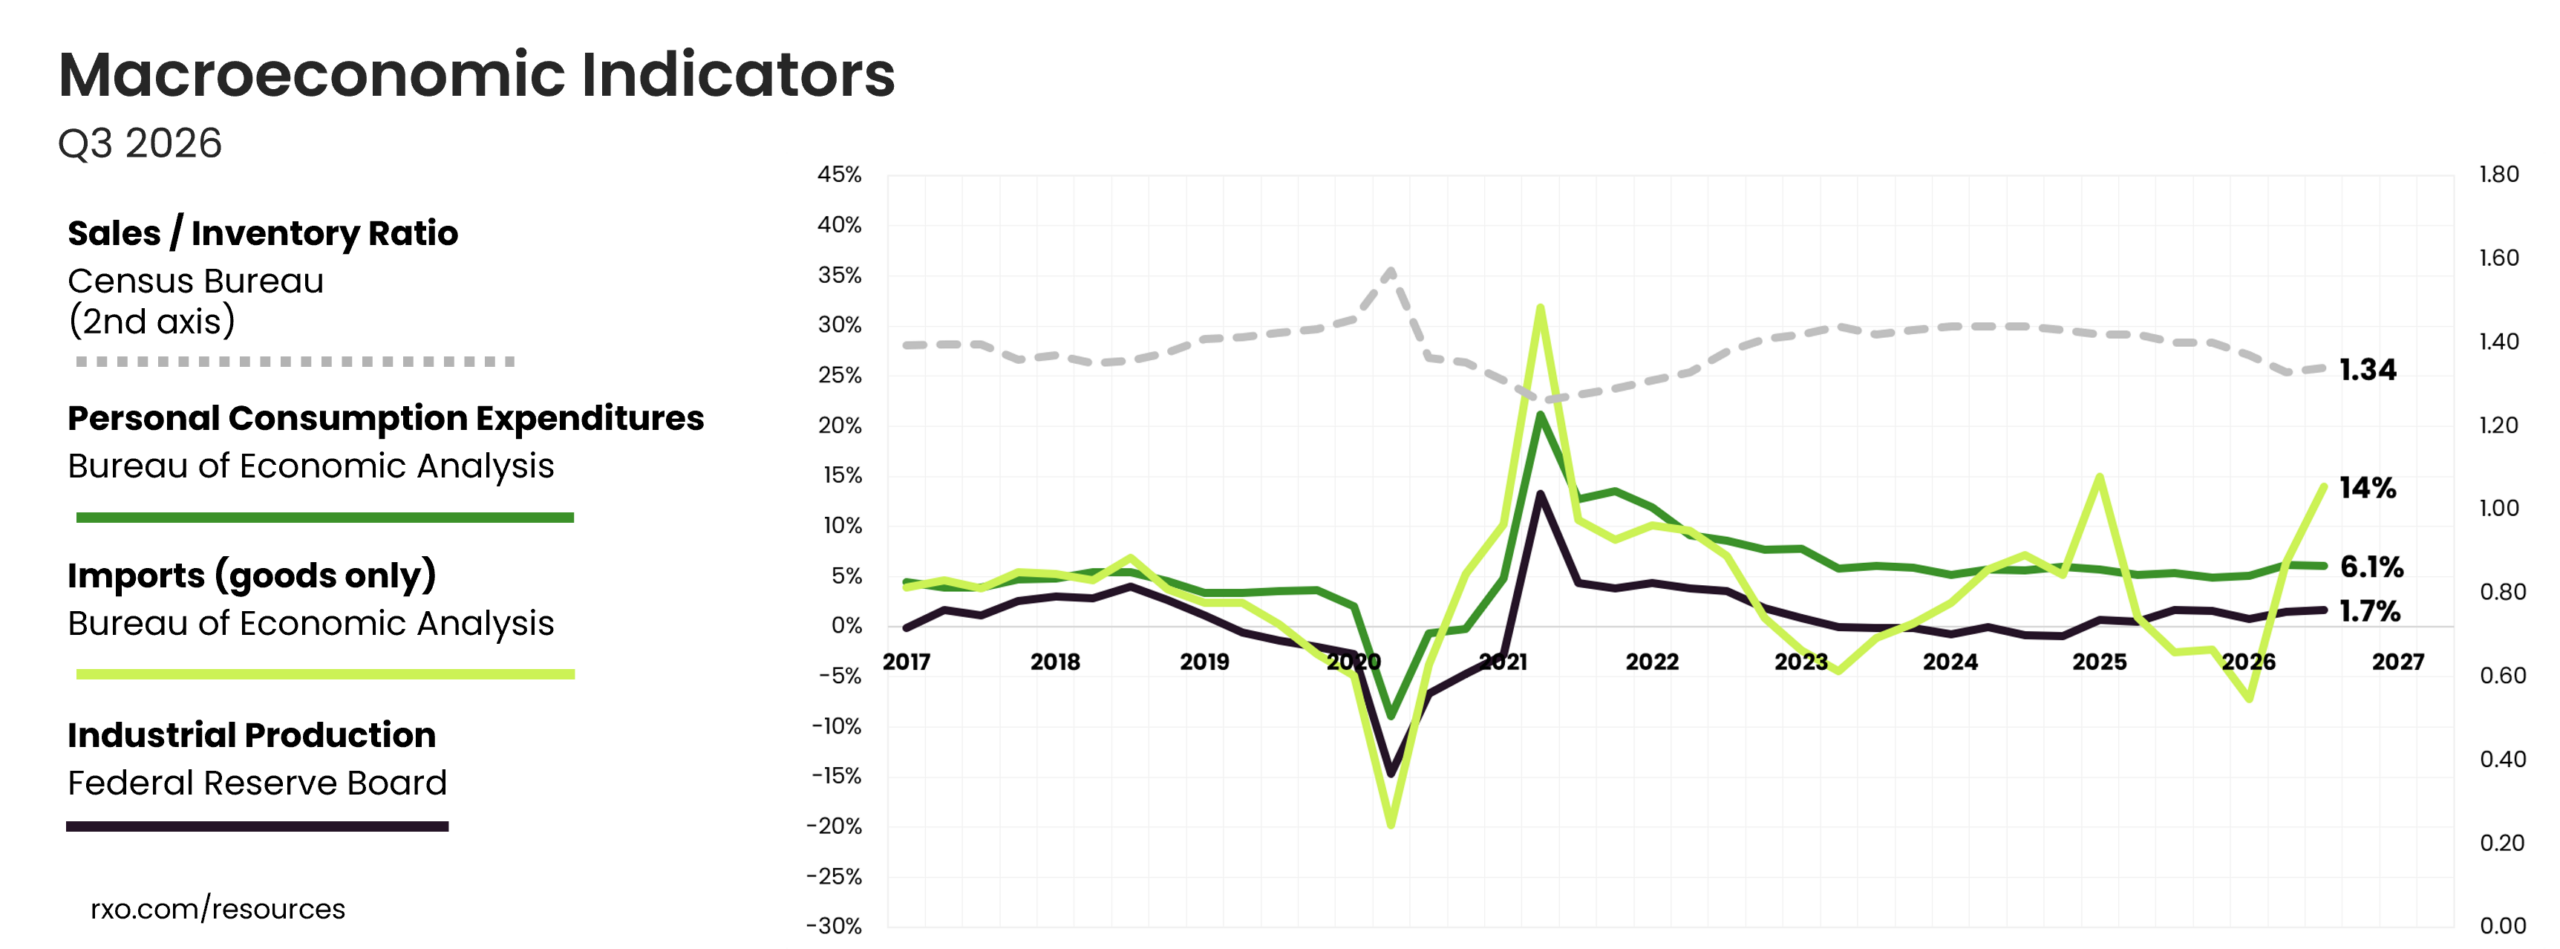
Let’s examine the most recent available figures for industrial production, consumer spending, imports and inventories through the lens of how they are impacting truckload shipping.
Download all the Curve charts for your next presentation.
Note: Truckload Market Inflation/Deflation vs. Economic Growth/Recession
It’s worth noting that though the truckload market is linked to what happens in the wider economy, the two are not always coupled.
Given how supply and demand work in the truckload market, it’s possible for the economy to remain strong and the truckload market to languish. It’s also possible for the truckload market to inflate while the economy weakens (see the inflationary Curve in 2008 during the Great Recession).
More specifically, carriers are contending with soft freight volumes amid a mixed macroeconomic backdrop, yet freight rates are rising, driven by higher operating costs (fuel, labor, insurance) and a diminished driver pool that has tightened capacity (more on that below).
Personal Consumption Expenditures
- What is it?
How much the American consumer is spending - How it impacts truckload shipping:
The more we buy, the more we need to produce (IP) and/or buy elsewhere (imports), which translates to greater demand for truckload shipping.
While we’ve had more than five years of above-target inflation and fears of a possible recession, consumer spending has held up, providing a steady base for the overall economy.
In Q3, personal consumption expenditures were up 6.1% year-over-year, similar to the growth rate in Q2. However, more than half of that reflects higher prices; adjusted for inflation, spending rose about 2.5%.
Industrial Production (IP)
- What is it?
Total value of physical goods America is producing - How it impacts truckload shipping:
The more we make, the more freight that needs to move, from raw material inputs to finished goods
After remaining in slightly negative territory year-over-year for six consecutive quarters, Industrial Production was positive for all of 2025 and finished the year up 1.6% in Q4.
In Q3 Industrial Production rose slightly to 1.7% year-over-year, compared to 1.5% in Q2.
Imports (Goods Only)
- What is it?
Total value of physical goods America is buying from other countries - How it impacts truckload shipping:
The more we buy from other countries, the more freight that needs to move, from raw material inputs to finished goods
After a short-term increase driven by tariffs in Q1 2025 (many shippers were scrambling to replenish inventories with non-tariffed goods before updated trade policies set in), imports came back down to earth throughout 2025.
Imports (of goods, excluding services) ended Q1 2026 at -7.2%, but rebounded in Q2 to 6.4%, and to 14% in Q3, reflecting more favorable year-over-year comparisons, potential restocking efforts, and a trade economy that has somewhat adapted to over a year of trade volatility.
Inventory-to-Sales
- What is it?
The ratio of physical goods businesses have in stock vs. how much they’re selling - How it impacts truckload shipping:
When inventory levels are high, it creates a delay in demand for truckload shipping, as businesses will work off excess inventory before producing new goods (IP) or buying more goods (imports).
After peaking at 1.44 in Q3 2024, the inventory-to-sales ratio gradually trended down, sitting at 1.33 in August 2026 (latest available).
With so much economic uncertainty amidst muted consumer demand, shippers have been hesitant to build up big piles of inventory. However, now that inventories are relatively depleted and peak season is approaching, there have been some modest restocking efforts.
To the extent that consumer demand improves, supply chain leaders may need to undertake more significant restocking efforts to rebuild inventory levels (which would result in increased truckload demand).
Macroeconomy & the Truckload Market: Key Takeaways
- Despite continued headwinds over the past three years, the U.S. economy has avoided a recession (at least for the time being), supported by stable consumer spending and a strong industrial recovery.
- We are operating in a fluid environment — trade policy, geopolitical unrest, and higher oil prices are driving significant economic uncertainty, which has led to near-record low consumer confidence and long-term inflation expectations that remain elevated.
- There are a few signs for optimism in the current environment, including ten straight months of manufacturing expansion and a pickup in inventory heading into the holidays.
- The last time the freight cycle went inflationary (2020 – 2021), surging demand drove rate growth. Demand is not driving this inflationary leg — instead, supply-side constraints (carrier attrition) are the primary force.
- That said, any increase in demand, even modest, would drive further supply chain volatility.
Truckload Market Trends to Watch in Q4 2026
Let’s unpack a few of the key trends impacting the market before we dive into the updated Q forecast.
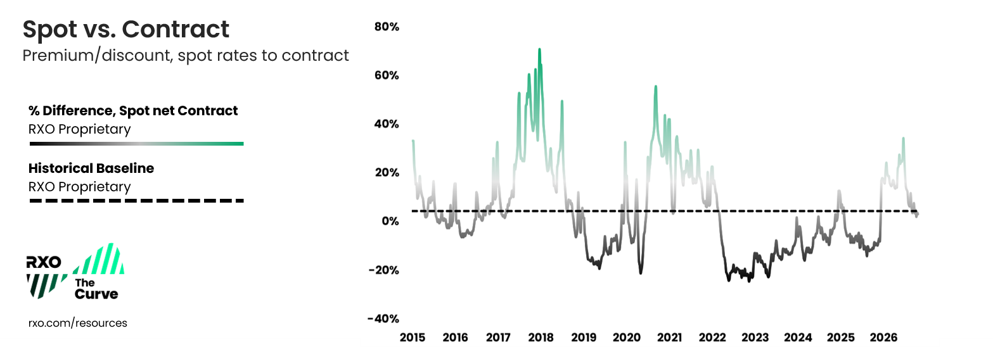
1. Despite continued spot rate inflation, contract rates are catching up.
Even though spot rates bounced off the bottom in 2023 and have risen year-over-year since early 2024, they were, in absolute terms, unable to consistently overtake contract rates.
That all changed at the very end of 2025, and spot rates have held their advantage throughout the first three quarters of 2026, driven by federal regulatory actions tied to driver eligibility and licensing (more on that below).
As this dynamic persisted, routing guides deteriorated as contract rates that were set in the softer market fell under pressure.
The prolonged spike in spot market volatility has pulled up contract rates (as is typical for this stage of the truckload market cycle), with many shippers even conducting mid-cycle transportation RFPs and mini-bids to adjust pricing.
More recently, with the increase in contract rates, coupled with a slight cooling of the spot market, the spread between the two is now closer to parity compared to earlier in the year.
2. Federal policy enforcement has eliminated carrier capacity.
The federal policy initiative to increase enforcement on non-domiciled CDLs, which is primarily aimed at the immigrant driver population, has significantly impacted the carrier market.
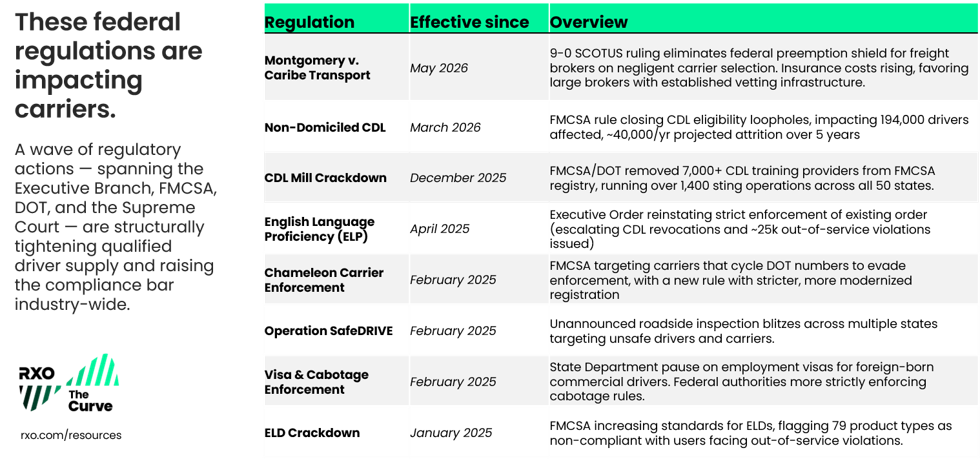
Let’s briefly unpack what’s going on with the most impactful regulation: non-domiciled CDLs.
Non-Domiciled CDLs
What is a non-domiciled CDL?
In brief, this type of state-issued CDL primarily applies to foreign nationals who are legally in the U.S., but not citizens or permanent residents. Note: This does not apply to Canada and Mexico, whose citizens must obtain their CDL from their home country.
A non-domiciled CDL gives these individuals the opportunity to drive in the for-hire truckload market, provided they complete an application, pass a driving test and provide authorization from U.S. Immigration.
What is happening to non-domiciled CDLs?
The FMCSA issued an interim final rule in late September, that, “Closes gaps in how states issue CLPs and CDLs to individuals from outside of the United States. It tightens eligibility, strengthens safeguards, and makes clear when these licenses must be canceled or revoked, delivering a more secure system and safer roads for all Americans.”
Or to put it simply for our context, it makes it significantly harder (or impossible) for many foreign nationals to drive a commercial vehicle in the U.S.
The FMCSA issued its final rule on February 13, which went into effect on March 16, 2026.
This rule significantly tightens eligibility by requiring specific, vetted employment authorization.
Employment authorization documents alone no longer qualify, and states must verify immigration status through the SAVE system. The rule also restricts non-domiciled CDLs to certain visa holders.
How much does this affect overall carrier capacity?
The FMCSA estimates that this will push nearly 200,000 drivers out of the market — approximately 5% of all active interstate CDL holders.
The massive and highly fragmented U.S. truckload market is notoriously difficult to quantify, particularly the subsection of the driver population to whom this rule applies (i.e., owner-operators and small fleets), so it’s difficult to say exactly how much this will ultimately impact truckload capacity.
How long will it take for the drivers to exit the industry?
While the final rule gives up to five years before the expiration of relevant CDLs, when combined with ramped up immigration enforcement and English Language Proficiency enforcement, it’s likely that many of the drivers in this population have already opted out of the industry.
Another consideration — insurance companies will be far less likely to extend coverage to carriers that employ non-domiciled CDLs, which would effectively push them out of the market regardless of more direct government enforcement.
Other Enforcement Considerations
In addition, increased immigration enforcement spending in the One Big Beautiful Bill Act, a crackdown on CDL mills and cabotage, and regulatory actions from the FMCSA and DOT have contributed to a noticeable reduction in the overall driver pool.
For reference, cabotage is the illegal practice of foreign truck drivers staying in the U.S. after a cross-border delivery to haul domestic loads. Federal enforcement has escalated sharply in 2026; the DOT now shares violation records with Customs and Border Patrol so they can revoke visas at the border.
The crackdown is taking capacity out of the U.S. truckload market, with the number of Mexican carriers active in southern border commercial zones down 4.3% between December and mid-May.
Taken together, these combined enforcement efforts represent the biggest structural change to the supply side of the truckload market since trucking deregulation in 1980. We expect these enforcement actions to continue driving even more capacity attrition.
3. Despite a more attractive spot rate environment, drivers are not flooding back into the market.
In previous market cycles, a prolonged period of spot rate inflation leads to a surge of capacity entering the for-hire trucking market.
Looking to take advantage of high-paying spot freight, private fleet and employee drivers shift to owner operators, CDL holders leave other jobs (construction, warehousing, etc.) for the cab of a truck, and fleets place orders for equipment replacement and expansion.
Eventually, this sets up a capacity overshoot, triggering a collapse in rates and the next deflationary leg of the cycle.
This time around, however, the dynamic is different. Though spot rates have been inflationary for several quarters, many carriers are still struggling with driver recruitment and elevated costs.
The combination of federal policy enforcement (covered above), increasing insurance premiums, record-high fuel, and high interest rates has both reduced the available labor pool while making the financial barriers to entry much higher.
The net result is a capacity base that is ill equipped to handle a dramatic spike in freight volume. As long as freight demand remains muted, there won’t be extreme market volatility, but any incremental increase in shipments could result in a very difficult market for shippers.
4. Though spot rates have increased, carriers are still less profitable than prior market peaks.
We’ve spent the last several years in a decidedly shippers’ market. With spot rates running hot for the past six months, the pendulum has swung the other way.
And while carriers are, broadly speaking, in a better position than they were a year ago, trucking companies are still facing increasing costs across the board: diesel, insurance, cost of capital, and labor.
Though freight rates have been increasing, they still haven’t kept pace with carriers’ cost inflation.
For reference, the cost to operate a truck excluding fuel is 29% higher compared to the last market peak in 2021, yet base rates (also excluding fuel) are approximately 15% lower.
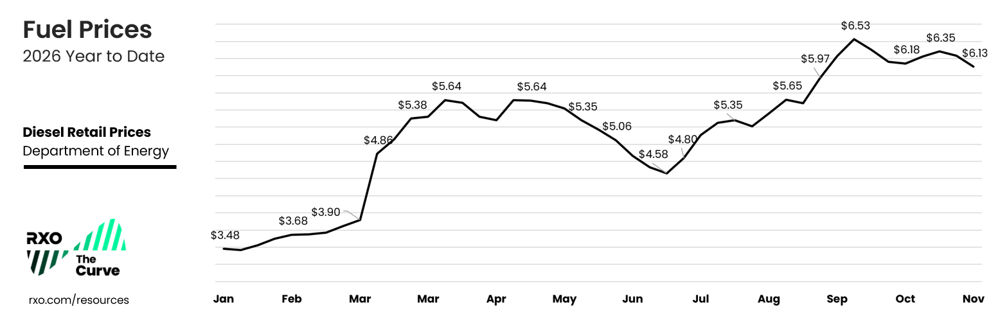
Then there’s diesel, which has risen 76% since the start of the year. In Q4 to date, it’s even 12% higher versus the Q3 average.
This is yet another inflationary pressure hampering carriers’ profitability.
Though spot freight is generally quoted in real time and with all-in (fuel inclusive) rates, the rate of change in fuel has far outpaced the rate of spot rate inflation.
Widespread routing guide deterioration and even higher spot rates are only being held in check by a muted demand picture.
5. Overall freight volumes are improving.
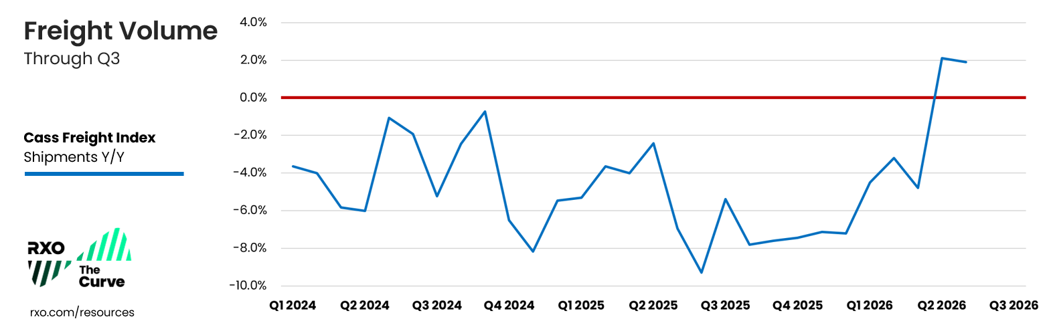
The Cass Freight Index, which measures truckload shipping volumes, has been year-over-year negative for 16 consecutive quarters.
While the Index was still slightly negative in Q3 (-0.3% year-over-year), the August and September readings were both slightly positive. Encouragingly, October shipments saw a stronger acceleration.
In fact, October shipments were up 5.9% year-over-year, accelerating from 1.9% in September, partly helped by an easy comparison. Slow growth in retail and industrial activity, inventory restocking ahead of the holidays, and to some extent, the IEEPA tariff refunds are all supporting activity.
It’s also worth noting that 2025 had relatively weak freight volumes, so it doesn’t take much to have incremental growth.
For a sustained move higher in freight demand, we would likely need to see lower inflation, a lower interest rate environment, and an improved housing market.
6. The supply / demand balance remains fragile, and susceptible to any volatility.
Accelerated carrier attrition over the past year has taken its toll, setting up a more challenging shipper’s market with increased rate volatility.
And though the market settled down throughout Q3, headwinds to capacity growth (targeted federal enforcement, high labor and insurance costs, high diesel) will keep the driver base from rapidly expanding.
Overall freight demand remains muted, however, with peak season approaching, stable industrial production data and relatively lean inventory positions, we could see a boost in shipping over the coming months.
Any improvement in truckload volume will likely create widespread capacity disruption.
Truckload Trends: Key Takeaways
- Though linehaul spot rates, from a year-over-year perspective, have cooled off compared to last quarter, they are still well into inflationary territory.
- Spot rate growth has pulled up contract rates, and the two are running closer to parity than earlier in the year.
- Federal policy enforcement targeting non-domiciled CDLs and other transportation regulations have significantly tightened the driver market.
- The capacity situation is much more fragile than at any point since 2022, and with policy enforcement, diesel prices and other cost increases (labor, insurance), rapid capacity growth is unlikely.
Q4 2026 Truckload Market Forecast
We’ve covered the macroeconomic environment, and key trends — but where does it leave us going forward?
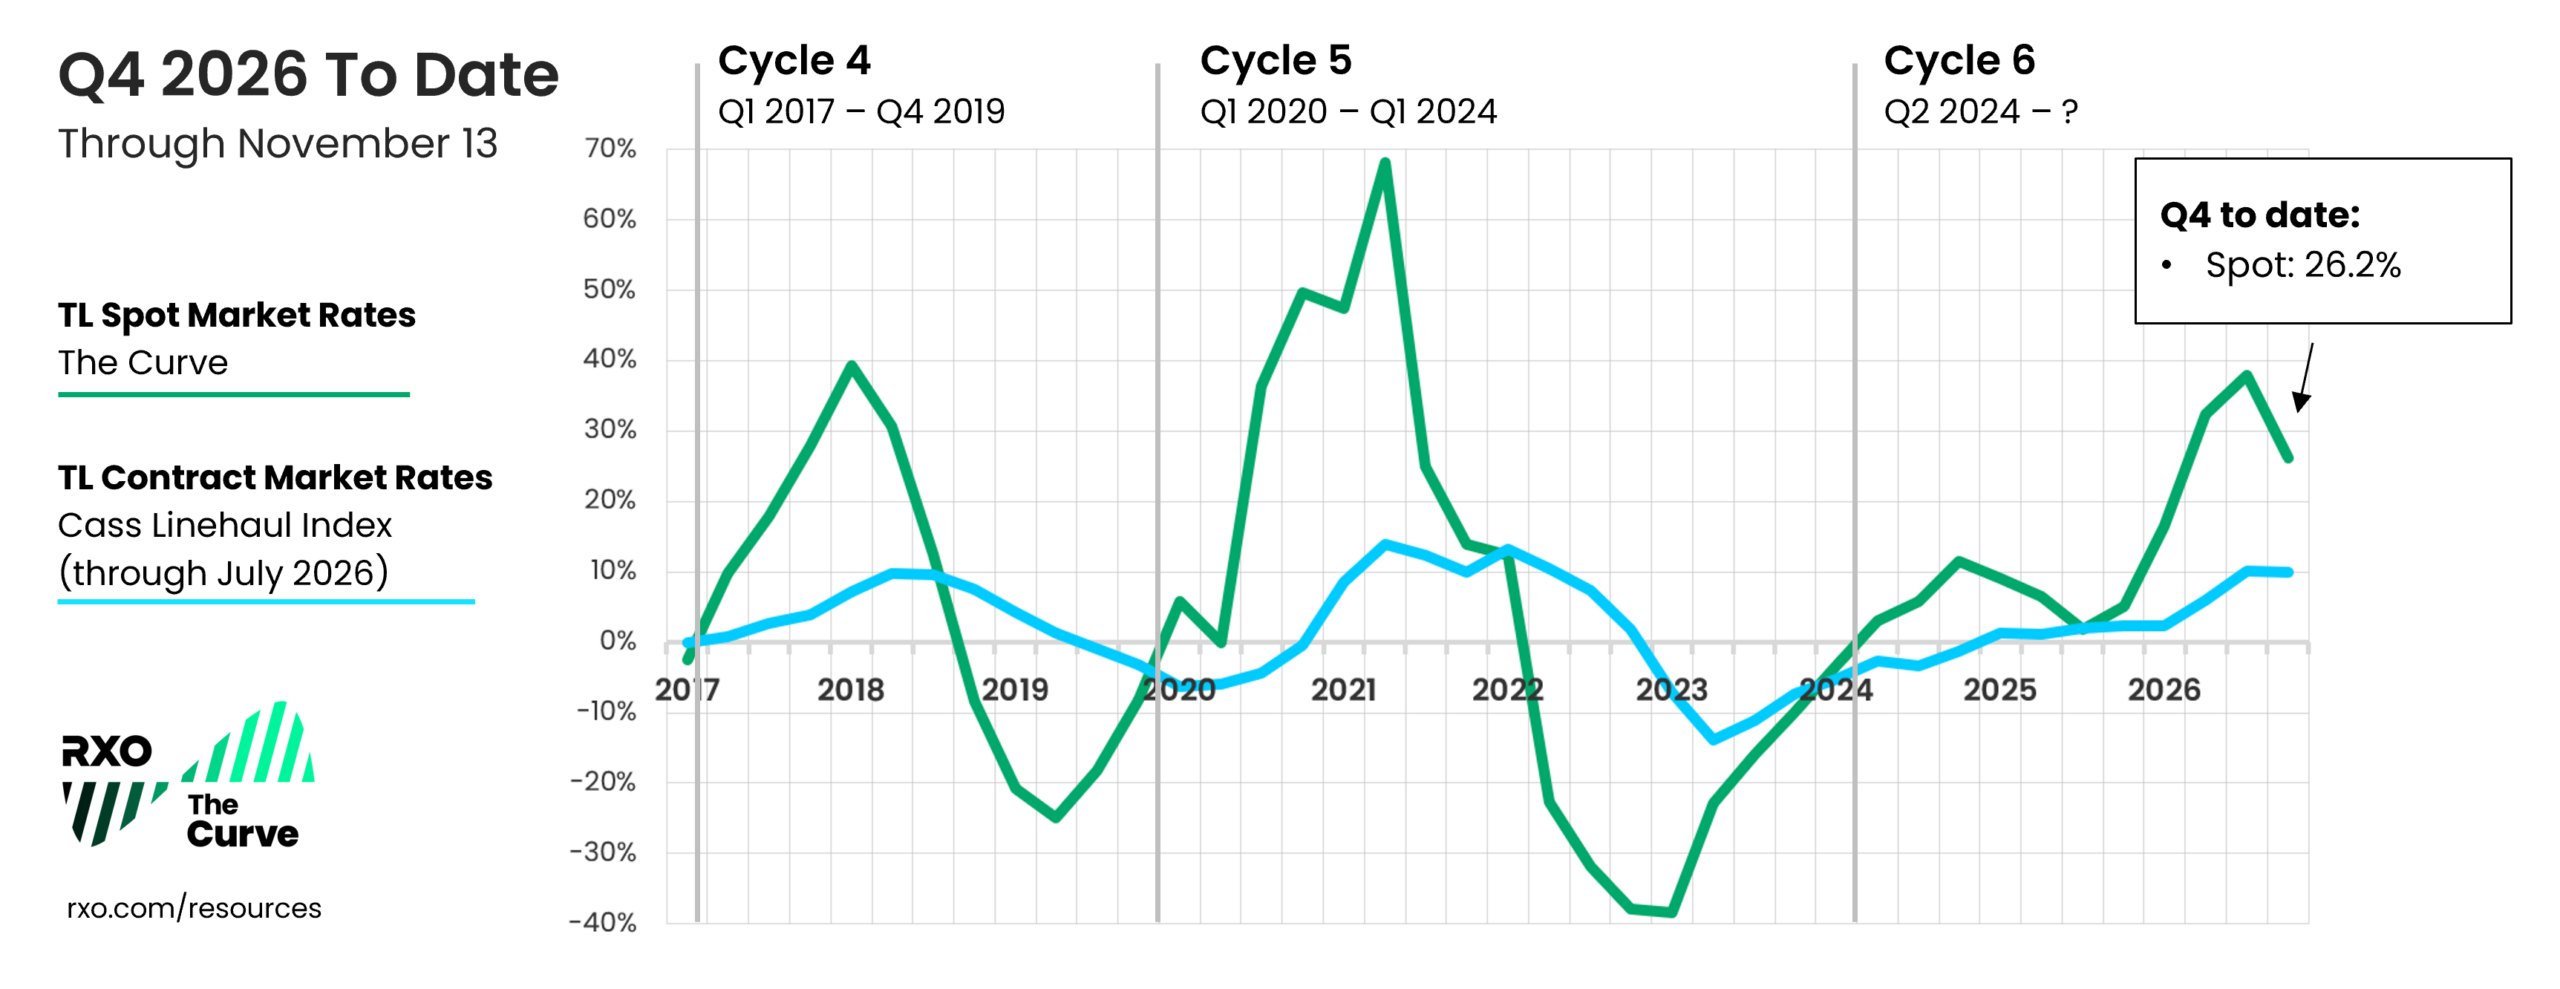
In Q4 to date, the Curve index is tracking below Q3, which begs the questions: has this truckload market cycle already peaked? Are we heading back into a deflationary market?
We don’t believe so and predict the Curve will continue to remain in inflationary territory.
Though we’ve seen a relative easing of rate and capacity volatility later in Q3 and Q4 to date, the baseline is still much higher than at this time last year.
After the initial spike in Q2, many shippers repriced their contractual freight at higher rates to better insulate themselves from the spot market, which has contributed to a reduction in tender rejections, not pricing.
Why we don’t believe we’re heading back to a deflationary spot market:
- Though the Curve may finish Q4 lower than Q3, it will still be up significantly year-over-year.
- The Curve measures year-over-year line haul spot rates (exclusive of fuel) — looking at all-in rates this quarter (fuel included), in absolute terms, spot rates are still up sequentially.
- It would be very difficult for freight rates to move much lower in the near future. In fact, given the current cost structure for carriers, it is likely rates will move even higher in 2027.
- We are not experiencing the typical influx of carrier capacity during a market peak (for reasons outlined earlier) which would increase supply and dilute pricing.
- Demand is currently muted. Any increase from peak season, and any improvement in 2027 (e.g., easing inflation, improving housing market, etc.) would drive the index even higher.
What shippers should expect moving forward
While it may feel like we’re in a relative lull compared to late Q2 and early Q3, we’re still in a very different shipping environment than at this point last year — the carrier market is in a much more precarious place than it has been over the last few years.
Though there has already been a significant impact, we expect carrier capacity to continue leaving the market with the full enforcement of the FMCSA Final Rule on non-domiciled CDLs in addition to other regulatory actions.
As stated previously, we believe this represents the biggest structural change to the U.S. carrier market since industry deregulation in 1980 — much more than the ELD mandate in 2017.
Furthermore, with rising insurance premiums, sky-high diesel prices, elevated interest rates, and expensive labor, we do not anticipate there will be an influx of capacity (as would be typical in this stage of a market cycle).
Though it’s unlikely that we’ll see a massive demand surge during peak season given the economic headwinds for the average U.S. consumer, there are a few reasons to be optimistic, including lower inventory positions and import growth.
If demand follows typical seasonality, we expect increased rate and capacity volatility to close out 2026.
Q4 2026 Forecast: Key Takeaways
- The Curve index will remain well into year-over-year inflationary territory, though it may finish down slightly from Q3.
- Though spot rates have moderated compared to earlier in the year, peak season is approaching with an expectation of seasonal rate volatility to end 2026.
- Rising carrier costs and tightening regulations will prevent a dramatic expansion of capacity, which typically occurs at this point in the cycle.
- We’re already in a fragile shipping environment, and though this has been a supply-driven recovery, any increase in demand will drive rates and volatility even higher.
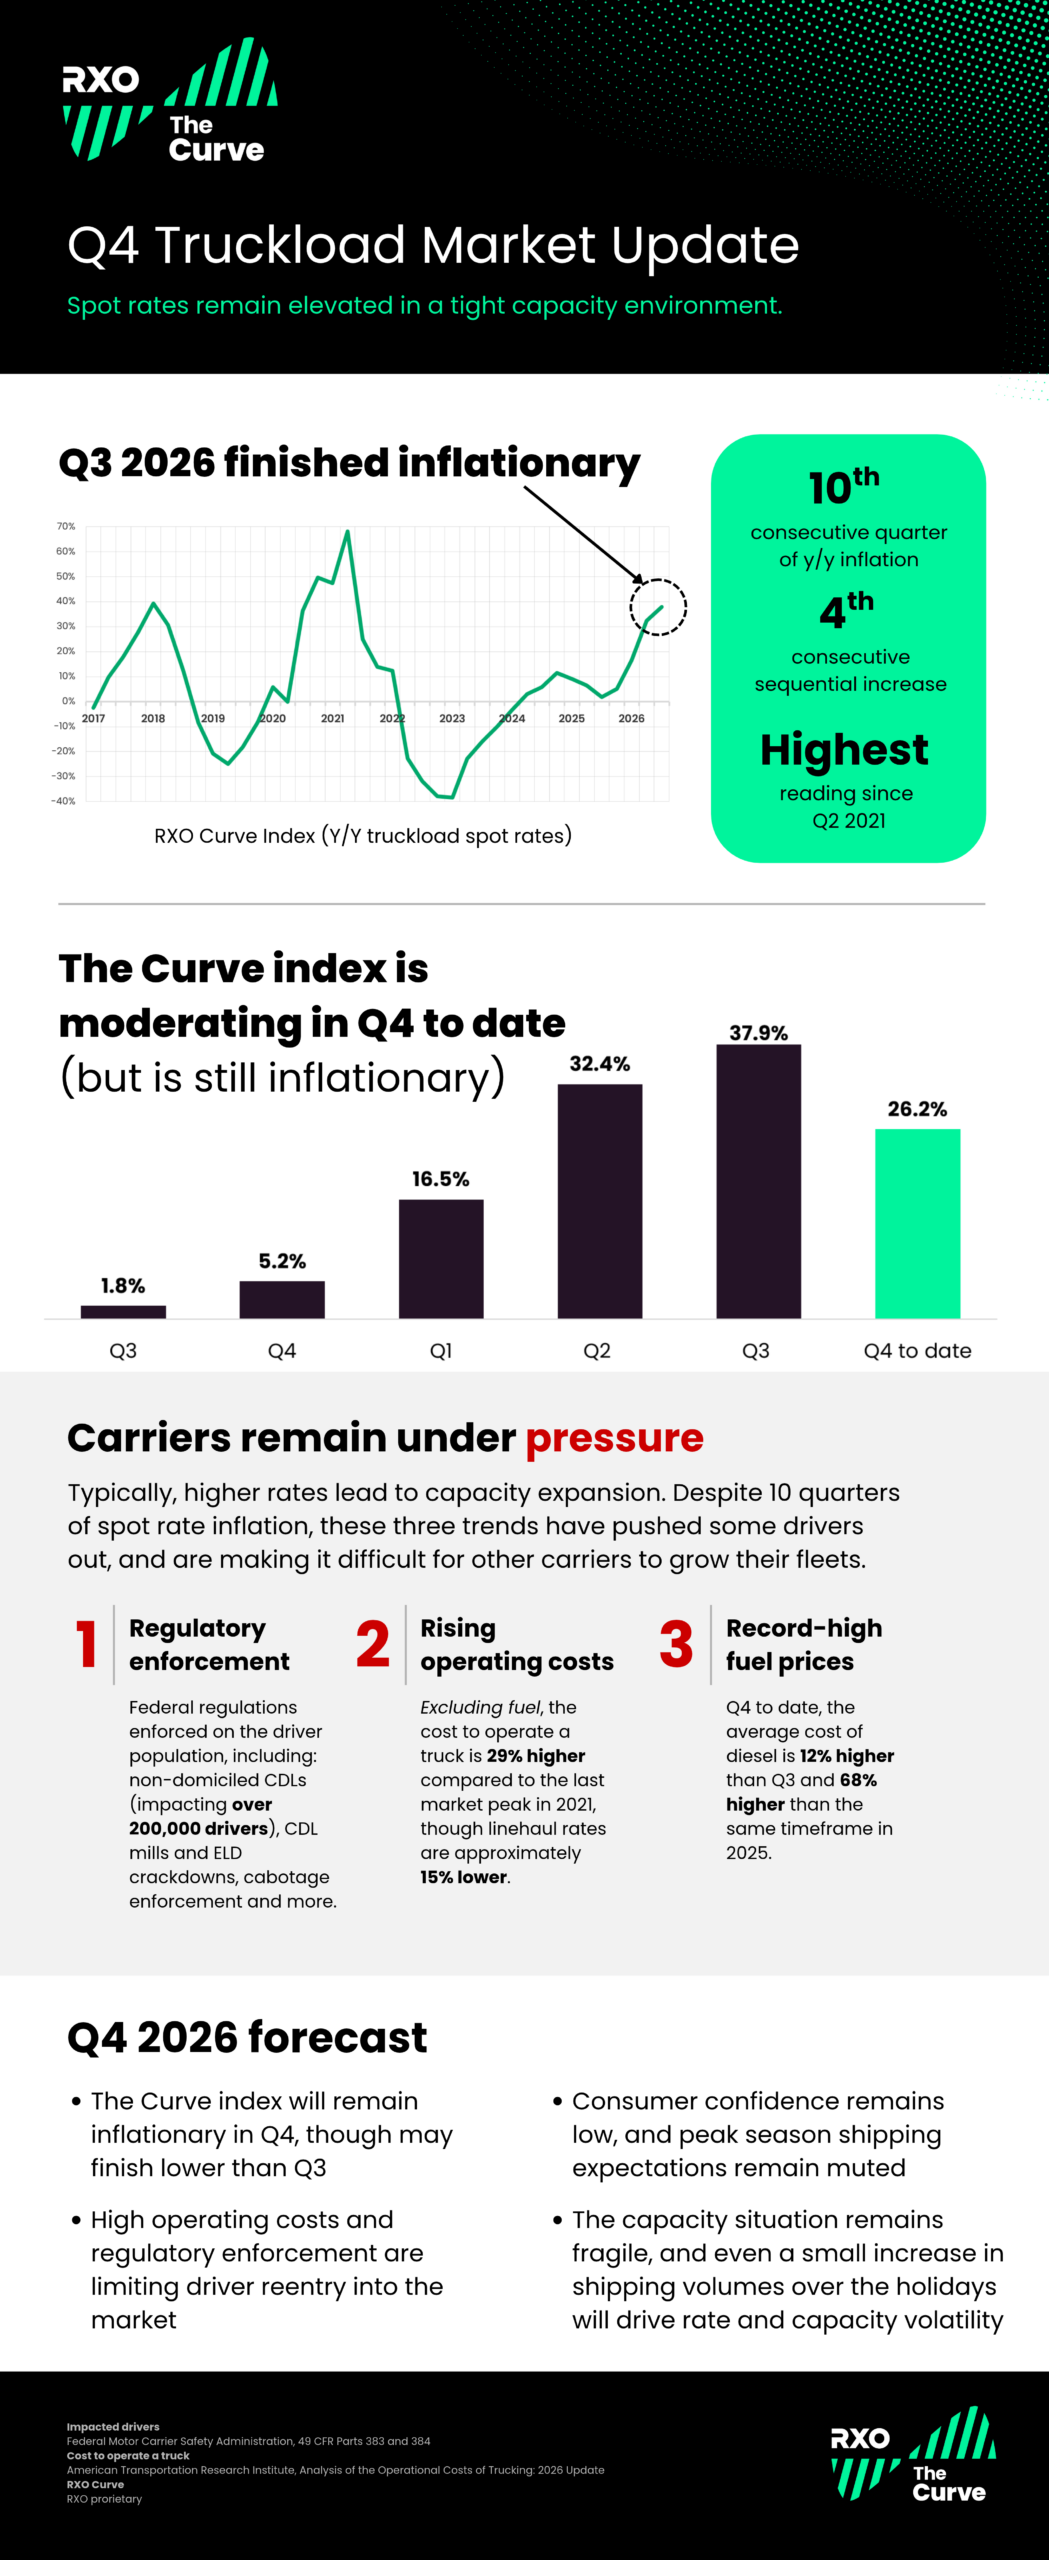
The Q4 2026 Truckload Market Trends Infographic
Next Steps: Get Your KPIs in Order With the Research
Did you know that 99% of carriers take shippers KPI expectations into account before agreeing to move a load with them?
As we head deeper into an inflationary market, it’s the perfect time to check yours up against industry standards.
The latest edition of our original, independent research study on logistics KPIs is loaded with insights and benchmarks, informed by 1,000 shippers and carriers.
Check out the research study now to start having a more data-driven network.